Shafie Insurance Brokers, Always by Your Side

With over 10 years of experience in the insurance industry

Insurance Purchase and Issuance Process

  01.

Contact and Insurance Needs Assessment

The policyholder contacts us by phone or visits in person to discuss their insurance needs. At this stage, the type of insurance, the nature of the risk, and the initial expectations are identified.

  02.

Professional Risk Assessment and Evaluation

Insurance specialists assess the client's circumstances, history, risk exposure, and technical requirements to determine the appropriate scope of coverage and identify critical insurance considerations.

  03.

Proposal Submission and Insurer Selection

Based on the assessment results, suitable proposals from reputable insurance companies are presented. After comparing coverage options, terms, and premiums, the policyholder selects the most appropriate insurer.

  04.

Proposal Presentation and Insurer Selection

Based on the risk assessment, tailored proposals from reputable insurance providers are presented. After reviewing the coverage options, terms, and premiums, the policyholder selects the most suitable insurance solution.

Our Services for You

Insurance Solutions

Img12

Auto Insurance

Auto insurance policies are designed to provide financial, bodily injury, and legal liability protection arising from road accidents. They represent one of the most essential risk management tools for vehicle owners. In general, auto insurance consists of two main categories: Third-Party Liability Insurance and Comprehensive Auto Insurance, both of which play a complementary role in protecting drivers, passengers, and third parties.

Third-Party Liability Insurance covers bodily injuries and property damages caused to third parties as a result of traffic accidents. In accordance with applicable regulations, this coverage is mandatory for all motor vehicles.

Comprehensive Auto Insurance is an optional policy that provides coverage for damages sustained by the insured vehicle due to events such as collisions, fire, explosion, total or partial theft, and other covered risks.

In addition to the standard coverages, policyholders may select a variety of supplementary protections, including glass breakage, natural disasters, vehicle depreciation, deductible reduction or elimination, and loss-of-use coverage. These options can be tailored according to the type of vehicle and the specific needs of the insured.

Icon5h

Fire Insurance

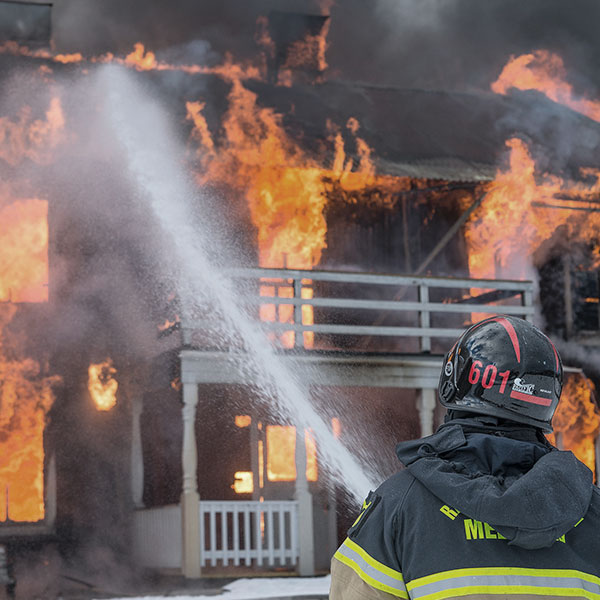
Fire insurance is one of the most essential risk management solutions for protecting properties, assets, and investments against unforeseen events. This type of insurance provides financial compensation for damages sustained by buildings, facilities, machinery, equipment, furnishings, and inventories in the event of covered incidents.

The standard coverages of fire insurance include fire, lightning, and explosion. Depending on the nature of the property and its risk profile, additional protections can be incorporated, including earthquake, flood and storm, burst water pipes, aircraft impact, burglary with forcible entry, landslide and subsidence, as well as damages resulting from civil unrest.

The scope of coverage, policy conditions, and insured values are determined based on risk assessment and the characteristics of the insured property. Selecting the appropriate coverage plays a significant role in ensuring business continuity and minimizing the financial impact of unexpected events.

Icon1h
Img11
Img13

Life Insurance

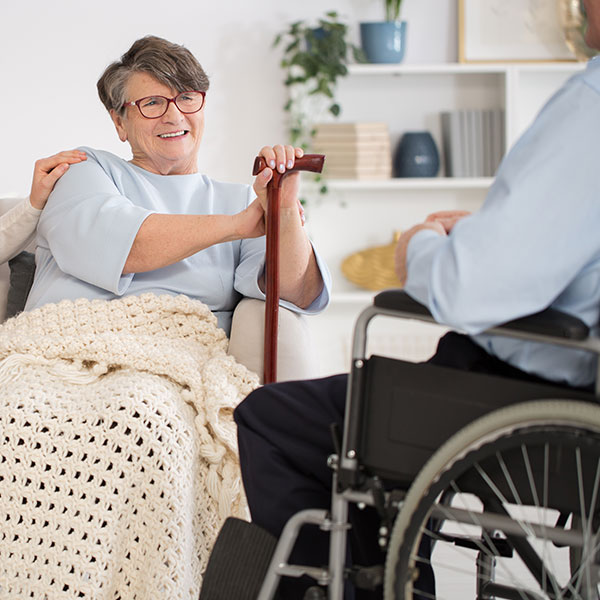
Life insurance is one of the most important financial planning tools for individuals and families, designed to provide long-term financial security throughout life and beyond. By combining insurance protection with savings and investment features, life insurance helps safeguard human capital and manage life-related risks effectively.

In addition to providing a death benefit to beneficiaries, life insurance policies may include a variety of coverages such as death from any cause, accidental death, permanent disability, critical illness coverage, dismemberment benefits, and premium waiver provisions. The policy's accumulated cash value and surrender value can also serve as a valuable financial resource for medium- and long-term planning objectives.

Coverage terms, insured amounts, and policy options are determined based on factors such as age, policy duration, financial goals, and the desired level of protection. Life insurance plays a significant role in ensuring peace of mind, supporting retirement planning, and providing financial protection for beneficiaries.

A life insurance policy represents an agreement between the policyholder and the insurer, under which the insurer commits to paying a specified amount upon the insured person's death in exchange for premium payments. Depending on the policy terms, benefits may also be triggered by events such as terminal illness or critical illness. Premiums may be paid regularly or as a lump sum, and additional expenses, including funeral costs, may also be covered under certain policy arrangements.
Icon4h