 Fa
 En

A fire, explosion, earthquake, flood, burst pipe or similar event can cause significant financial damage to a residential property in a short period of time. Household Insurance in Iran is designed to help reduce the financial impact of specified risks by covering the residential building, its installations, household contents, or a combination of them, depending on the selected policy.
The core of this insurance is generally residential fire insurance, where the basic insured risks commonly include fire, explosion and lightning. Additional risks such as earthquake, flood, storm, burst pipes and theft may be added depending on the insurer, policy terms and the coverage selected by the policyholder.
What Is Household Insurance?
Household Insurance in Iran is generally provided through a residential fire insurance policy designed to protect insured property against specified financial losses.
Depending on the needs of the customer, the policy may cover:
- the residential building
- household contents
- or both the building and contents
This means the insurance can be relevant to homeowners, tenants and owners of properties that are rented to others.
A homeowner may choose to insure the structure and fixed installations of the property, while a tenant may be more interested in protecting personal belongings and household contents.
It is important to understand that residential fire insurance is primarily designed to cover financial loss to insured property. Personal injury and bodily injury should not automatically be considered part of standard building and contents coverage.
What Can Household Insurance Cover?
Residential Building and Fixed Installations
When building coverage is selected, the policy may cover the residential structure and fixed installations described in the insurance contract.
Depending on policy terms, this may include:
- the residential structure
- fixed building installations
- permanent mechanical or electrical systems
- other fixed equipment defined in the policy
The insured value of the building should generally reflect the appropriate reconstruction value of the insured structure.
The market price of a property and the insured value of the building are not necessarily the same. In particular, the value of the land should not normally be confused with the reconstruction value of the building.
Household Contents and Personal Belongings
Household contents may also be insured separately or together with the building.
Depending on the policy, this category can include typical household belongings such as:
- furniture
- home appliances
- electronic equipment
- personal household items
- other contents specifically included within the insured property
High-value or special items such as cash, jewellery, precious metals, documents and certain valuable objects may be subject to separate conditions, limits or exclusions. Their coverage should therefore be confirmed before purchasing the policy.
Main Covers of Residential Fire Insurance
The three principal risks commonly associated with residential fire insurance are fire, explosion and lightning.
Fire
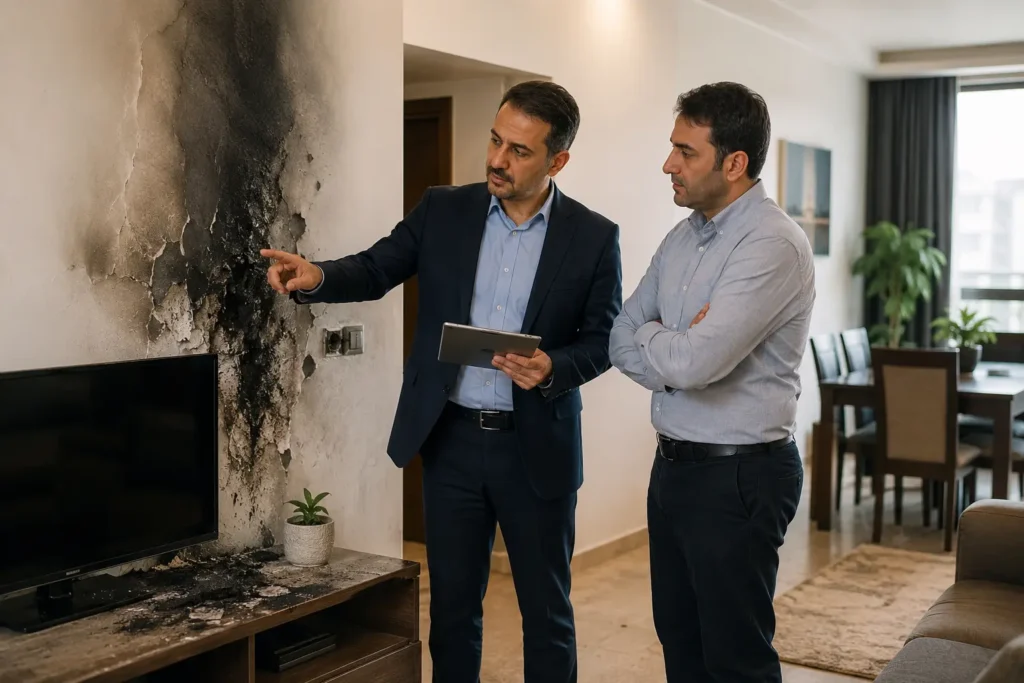
If an insured building or its contents are damaged by a covered fire, the loss may be assessed and compensated in accordance with the policy terms, insured value, applicable deductible and coverage limits.
Explosion
Damage resulting from an insured explosion may also be covered, provided that the event and the damaged property fall within the policy conditions.
Lightning
Direct damage caused by lightning is also generally considered one of the principal risks under residential fire insurance.
Optional Additional Covers
Basic fire insurance does not automatically cover every possible event that may damage a home.
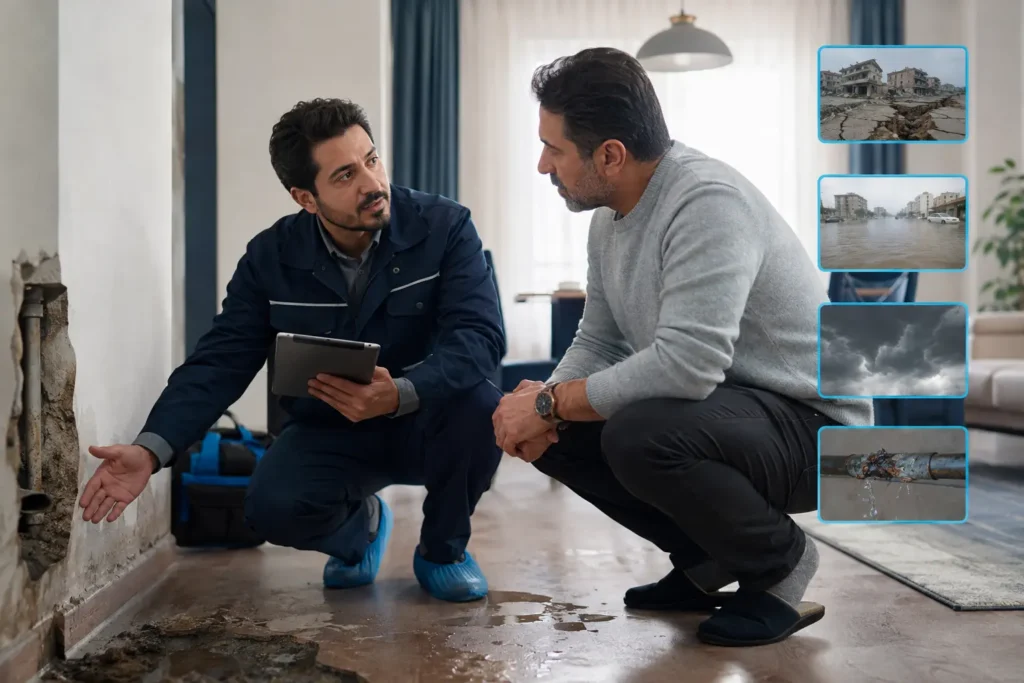
Risks such as earthquake, flood, burst pipes or theft typically need to be specifically included in the policy as additional coverage.
The exact list of optional covers can vary between insurers and insurance products.
Earthquake and Volcanic Activity
Earthquake coverage may be added to protect the insured property against financial damage resulting from an earthquake, subject to the terms and limits of the policy.
If earthquake protection is important to you, do not assume that the standard fire insurance policy automatically includes it. The coverage should be specifically confirmed in the issued policy.
Flood and Water Overflow
Flood and water overflow may also be offered as additional coverage.
When considering this protection, it is important to check:
- the exact insured event definition
- applicable deductibles
- geographical risk conditions
- coverage limits
- policy exclusions
Burst Water and Sewage Pipes
Damage caused by a burst water or sewage pipe can affect walls, ceilings, flooring, fixtures and household belongings.
This risk may be offered as an additional cover and should be reviewed separately when choosing the policy.
Theft
Theft may also be available as an optional coverage under certain household insurance policies.
However, not every case of missing property or theft will necessarily be covered.
Policies may include specific requirements concerning the circumstances of the theft, evidence of forced entry, insured items and other policy conditions. The exact terms should therefore be reviewed before the policy is issued.
Storm and Similar Risks
Depending on the insurance product, additional coverage may also be available for risks such as:
- storm
- whirlwind
- strong wind
- heavy rain-related damage
- weight of snow
The scope and availability of these covers can differ between insurers.
Other Optional Covers
Other additional protections may also be available depending on the policy, including:
- accidental glass breakage
- aircraft or helicopter impact
- falling aircraft parts
- landslide or subsidence
- avalanche
- impact by external objects
- debris removal expenses
Each additional cover may have its own deductible, limit and conditions.
Household Insurance for Homeowners and Tenants
The insurance needs of a homeowner and a tenant are not always the same.
For Homeowners
Homeowners usually have an insurable interest in the residential building and fixed installations.
They may choose to insure:
- the building
- the fixed installations
- household contents
- or all of them together
For Tenants
Tenants do not normally own the building itself, but they may wish to insure their own household belongings and personal contents.
Depending on the available insurance product, contents-only coverage may be suitable for tenants.
For Owners of Rented Properties
If you own a property that is rented to another person, it is important to distinguish between the building owned by you and the personal belongings owned by the tenant.
The relevant insurance responsibilities should be clarified before arranging the policy.
What May Not Be Covered?
Having Household Insurance does not mean that every type of damage will automatically be compensated.
Coverage depends on:
- the risks selected in the policy
- the insured property
- policy exclusions
- deductibles
- insured sums
- coverage limits
- the cause and circumstances of the loss
For example:
- A risk that has not been added to the policy may not be covered.
- Property that is not included in the insured property definition may be excluded.
- A loss exceeding the insured sum or policy limit may not be fully compensated.
- Certain valuable items may have specific conditions or exclusions.
- Bodily injury is not the same as financial damage to the insured building or contents.
The issued policy wording, including its general and specific conditions, should always be reviewed before purchase.
How Is the Cost of Household Insurance Determined?
There is no single fixed price for Household Insurance in Iran.
The premium may depend on several factors, including:
- insured value of the building
- insured value of household contents
- size of the property
- type of construction
- location of the property
- selected additional covers
- insured sums and coverage limits
- risk characteristics of the property
- applicable deductibles
- underwriting conditions of the insurer
Adding additional protections such as earthquake, flood or theft may also affect the final premium.
For this reason, the property information and required covers should first be reviewed before an insurance quotation can be prepared.
How Should the Building Sum Insured Be Calculated?
One of the most important points when arranging home insurance is selecting a realistic insured value.
The building sum insured should not simply be based on the property’s market selling price.
For building insurance, the focus should generally be on the value of the insured structure and an appropriate reconstruction cost rather than the value of the land.
For household contents, the policyholder should also make a realistic estimate of the value required to replace the insured belongings.
Underestimating the insured value may affect the amount payable in the event of a claim, depending on the terms of the policy.
What Information and Documents Are Required?
The exact information and documents required can vary depending on:
- the insurer
- type of residential property
- requested coverage
- property value
- risk characteristics
You may generally be asked to provide information about:
- the applicant
- property address
- type of residential property
- floor area
- construction type
- estimated building value
- estimated household contents value
- requested optional covers
If additional documents or information are required, our insurance specialist will inform you after reviewing the request.
How to Apply for Household Insurance
1. Submit Your Request
Complete the application form with:
- full name
- phone number
- additional details about your request
2. Speak With an Insurance Specialist
An insurance specialist will contact you to collect any additional information required about the property, building value, household contents and requested coverage.
3. Review the Risks and Coverage
Based on your property information, the available basic and optional covers can be reviewed.
4. Receive an Insurance Proposal
Once the necessary information is available, the proposed insurance terms and premium can be provided based on the insurer’s assessment.
5. Policy Issuance
After the terms are approved and the required steps are completed, the insurance policy can be issued.
What to Check Before Choosing a Policy
Price should not be the only factor when comparing Household Insurance policies.
A lower-priced policy may have a different insured sum, deductible, coverage limit or list of insured risks.
Before purchasing, check the following:
- Is the building insured?
- Are household contents included?
- What is the insured value of each section?
- Is earthquake coverage included?
- Is flood coverage included?
- Is burst pipe damage covered?
- Is theft coverage required and included?
- What deductibles apply?
- What risks are excluded?
- What are the maximum limits of the insurer’s liability?
Common Mistakes When Insuring a Home
One common misunderstanding is assuming that fire insurance only covers fire.
Another is assuming that a basic fire insurance policy automatically includes earthquake, flood, theft and all other possible risks.
Neither assumption is necessarily correct.
Other common mistakes include:
Underinsuring the Building
Declaring a building value that is significantly below its actual insurable value may cause problems when a claim is assessed.
Underestimating Household Contents
The combined replacement cost of furniture, appliances and other household belongings may be much higher than expected.
Choosing Coverage Without Considering the Property
The insurance needs of an apartment on a high floor may differ from those of a detached house or a property located in an area with higher exposure to flooding or other hazards.
The most suitable policy is therefore the one that reflects the actual characteristics of the property and the risks you want to protect against.

Summary
Household Insurance in Iran helps manage the financial risks associated with damage to residential buildings and household contents.
The standard foundation of this insurance generally includes fire, explosion and lightning, while additional risks such as earthquake, flood, burst pipes, theft and other perils may be added when available and required.
The most important consideration is not simply choosing the largest number of covers. The insured values, policy conditions, deductibles and selected risks should match the actual property and your needs.
To review your property and available coverage options, complete the Household Insurance Request form. An insurance specialist will contact you to discuss the next steps.