 Fa
 En
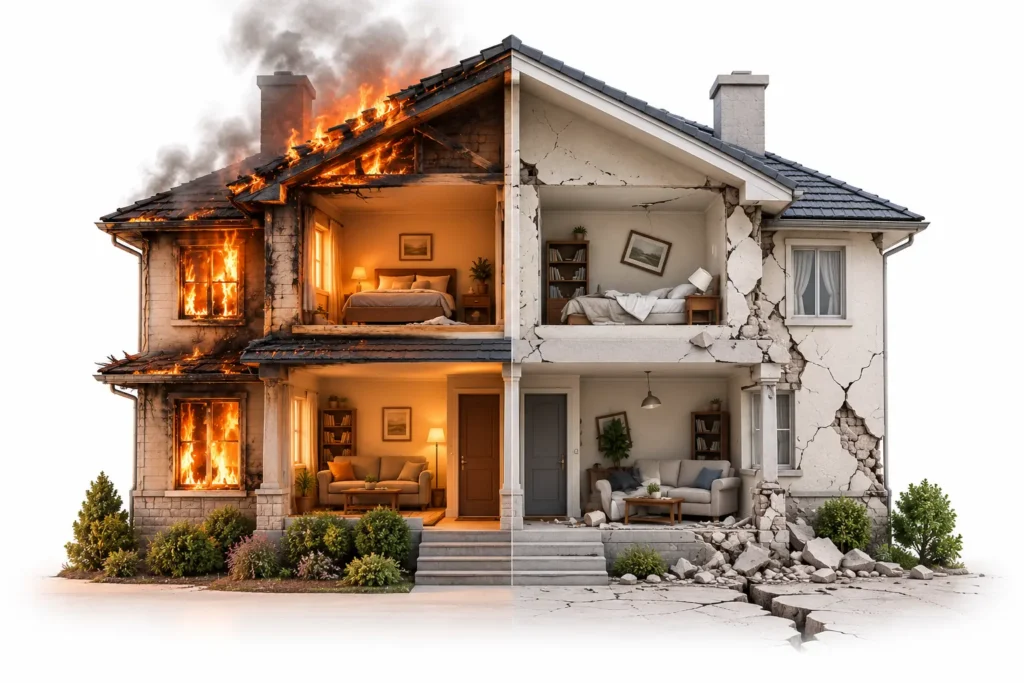
Fire insurance and earthquake insurance are not necessarily two completely separate insurance policies in the Iranian market. Basic fire insurance generally covers fire, explosion, and lightning, while earthquake is usually treated as an additional or supplementary risk that must be specifically selected and included in the policy.
In simple terms, what people commonly call “earthquake insurance” is often earthquake coverage added to a fire insurance policy.
This means that simply having fire insurance does not automatically mean your home is insured against earthquake damage.
The exact terms, deductible, sum insured, coverage limit, and exclusions may vary between insurers and policies, so the wording of the actual insurance contract should always be reviewed carefully.
Fire Insurance vs Earthquake Insurance at a Glance
The most important difference is the type of risk covered.
Basic fire insurance is designed to protect insured property against specific core risks, generally including fire, explosion, and lightning.
Earthquake, on the other hand, is commonly classified as an additional risk that can be added to the fire insurance policy.
| Topic | Basic Fire Insurance | Earthquake Coverage |
|---|---|---|
| Coverage type | Core coverage | Usually additional coverage |
| Main risk | Fire, explosion, lightning | Earthquake-related damage |
| Separate selection required | Usually no for core risks | Usually yes |
| Building | If the building is insured | If earthquake cover applies to the building |
| Contents | If contents are insured | If earthquake cover applies to contents |
| Deductible | Based on policy terms | May have separate conditions |
| Premium | Based on insured value and risk | Usually added to the base premium |
| Exact conditions | Defined in the policy | Depends on insurer and earthquake clause |
What Does Fire Insurance Cover?
Main Fire Insurance Risks
The core risks commonly associated with fire insurance are:
- fire
- explosion
- lightning
Fire insurance is primarily a form of property insurance. Its purpose is to compensate for financial loss to property specifically listed and insured under the policy.
For a residential property, the insured property may include:
- the building only
- household contents only
- or both the building and contents
The exact scope depends on what has been declared and accepted as insured property.
Why Earthquake Is Usually Not Part of Basic Fire Cover
Earthquake is generally treated as an additional risk rather than part of the standard fire insurance coverage.
This means the policyholder usually needs to specifically select earthquake protection and ensure that it appears in the policy schedule, special conditions, or endorsements.
Therefore, saying:
“I have fire insurance”
is not enough to conclude that earthquake damage is also insured.
The more useful question is:
“Is earthquake risk specifically included in my policy?”
What Does “Earthquake Insurance” Mean in Iran?
In the Iranian insurance market, the term “earthquake insurance” often refers to earthquake coverage added to a fire insurance policy.
For this reason, it is better not to rely only on the name of the insurance product.
Instead, review the actual list of insured risks.
Look for wording related to:
- earthquake
- earthquake and volcanic activity
- supplementary natural disaster coverage
- relevant endorsements or clauses
The exact terminology can vary between insurers.
This distinction is important because many policyholders assume that “home fire insurance” automatically protects them against all major natural disasters.
That assumption can lead to problems when a claim occurs.
Does Fire Insurance Automatically Cover Earthquake Damage?
Not necessarily.
If a policy only includes the main fire insurance risks—such as fire, explosion, and lightning—you should not assume that direct earthquake damage is covered.
Earthquake coverage normally needs to be specifically included.
In addition, when one event triggers another—for example, an earthquake followed by a fire—the claim cannot always be assessed simply by looking at the name of the event.
Factors such as the cause of loss, the policy wording, the selected earthquake clause, exclusions, and the insurer’s claim assessment may all affect coverage.
This is why the insurance contract itself remains the main reference when determining whether a specific loss is covered.
What Property Can Earthquake Coverage Protect?
Earthquake coverage does not automatically apply to everything inside or around a home.
You must first determine what property has been insured.
The Building
If the building and its fixed installations are listed as insured property and earthquake coverage has been selected for them, eligible earthquake-related damage may be assessed under the terms of the policy.
For building insurance, the insured value is generally linked to the value of the insured structure and rebuilding cost rather than the total market value of the property.
This distinction matters because the market price of a home may include the value of the land, which is not the same as the rebuilding value of the insured structure.
Household Contents
Household contents may also be insured separately or together with the building.
However, the contents must generally be included in the insured property and declared within the insured amount.
For example, if a policy covers only the building, you should not assume that furniture, appliances, and personal belongings are automatically protected simply because earthquake coverage has been added.
To understand your protection, ask three separate questions:
- Is earthquake coverage included?
- Is the building insured, the contents, or both?
- What insured value has been assigned to each category?
Practical Examples of How the Coverage Differs
Scenario 1: A Kitchen Fire
A covered fire damages part of the kitchen, walls, and household appliances.
If the building and contents are properly insured under a fire insurance policy, the eligible damage may be assessed under the main fire coverage, subject to policy terms, limits, and exclusions.
Earthquake coverage is not relevant in this scenario.
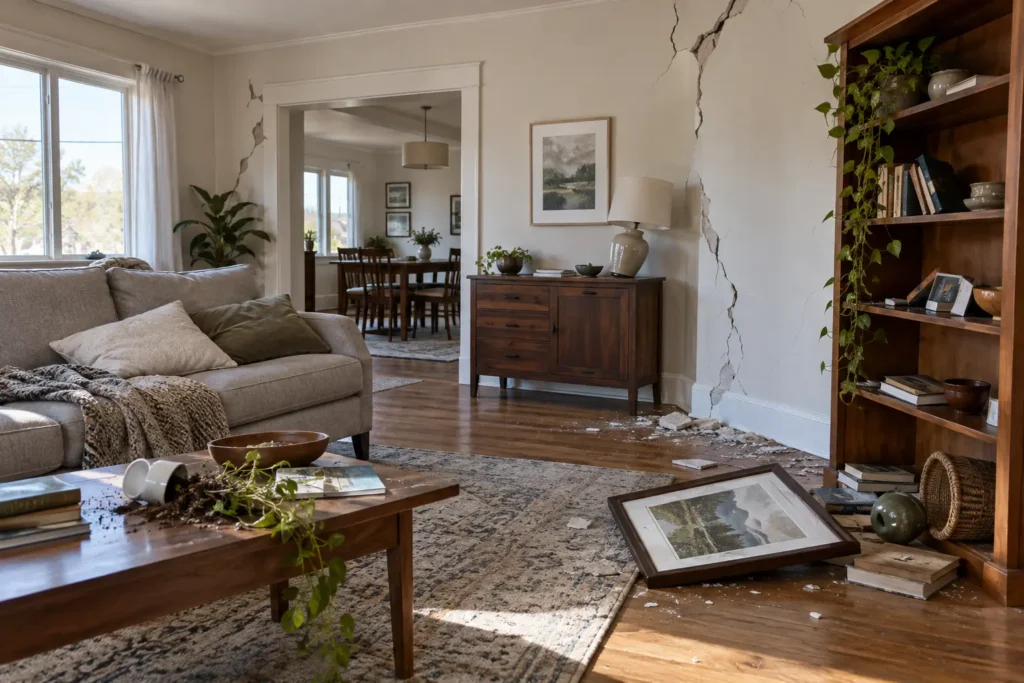
Scenario 2: Wall Cracks and Structural Damage After an Earthquake
A homeowner has basic fire insurance but did not add earthquake coverage.
An earthquake causes cracks in the walls and structural damage.
In this case, the policyholder should not assume that the damage will be covered simply because a fire insurance policy exists.
The earthquake risk must generally be included in the policy.
Scenario 3: Earthquake Coverage Exists, but Only the Building Is Insured
An earthquake damages both the building and household belongings.
The policy includes earthquake protection, but only the building is listed as insured property.
In this situation, earthquake coverage does not necessarily mean both types of loss are covered.
The status of the household contents may be different from the building.
Scenario 4: The Building Is Significantly Underinsured
Earthquake coverage has been selected, but the insured value of the building is much lower than the actual rebuilding cost.
Even though earthquake coverage exists, the declared sum insured still matters.
Underinsurance may affect the amount payable in a claim, depending on the policy conditions and applicable insurance rules.
Selecting the right coverage is therefore only one part of the process.
The insured value must also be appropriate.
Earthquake Coverage vs Iran’s Basic Natural Disaster Building Insurance
There is another important distinction in Iran.
Under the framework of Iran’s Natural Disaster Insurance Fund, a basic natural disaster insurance mechanism exists for eligible residential buildings.
Earthquake is among the natural disasters addressed within this system.
The purpose of this mechanism is to provide basic financial compensation for part of the damage to eligible residential buildings.
This should not be confused with earthquake coverage voluntarily added to a commercial fire insurance policy.
These are different insurance mechanisms.
In practical terms, users should distinguish between:
- basic fire insurance
- optional earthquake coverage added to fire insurance
- basic natural disaster building insurance
They may differ in structure, coverage, funding, limits, and claims processes.
This distinction becomes especially important when the value of the building or household contents is significantly higher than the protection provided by a basic scheme.
What Should You Check Before Adding Earthquake Coverage?
Insured Property
First, determine exactly what you want to insure:
- the building
- fixed installations
- household contents
- or a combination of these
A policy should clearly identify the insured property.
Sum Insured
Having earthquake coverage is not enough on its own.
The insured amount should also reasonably reflect the value of the insured property.
For buildings, the sales price of the property is not necessarily the correct figure to use because it may include the land value.
For household contents, it is useful to consider the approximate replacement value of furniture, appliances, and other insured belongings.
Deductible
A deductible is the portion of an eligible loss that remains the responsibility of the policyholder under the policy terms.
Additional risks such as earthquake may have their own deductible structure.
You should therefore check the deductible stated in the actual insurance contract rather than relying on a general percentage or assumption.
Coverage Limit
Review the maximum amount the insurer is responsible for paying.
Some policies may include separate limits for specific types of property or additional risks.
The exact amount should be confirmed from the policy schedule and special conditions.
Exclusions and Special Conditions
Not every loss occurring during or after an earthquake is automatically covered.
Coverage may depend on:
- how the damage occurred
- whether the damaged property was insured
- exclusions
- coverage limits
- deductibles
- endorsements
- special policy conditions
Because policy terms differ between insurers, general information should not replace a review of the actual insurance contract.
How Can You Check Whether Your Current Policy Includes Earthquake Coverage?
Do not rely only on the policy title.
Review the sections covering:
- insured risks
- special conditions
- endorsements
- insured property
- insured values
- deductibles
- coverage limits
- exclusions
Look for wording related to earthquake and volcanic activity or another equivalent term used by the insurer.
Then ask:
- Is earthquake explicitly listed?
- Does the coverage apply to the building?
- Does it apply to household contents?
- Are both included?
- What is the insured value of each?
- What deductible applies?
- Is there a separate earthquake coverage limit?
- Are there specific exclusions or clauses?
If any of these points are unclear, it is better to ask the insurer or an insurance advisor before a loss occurs.
For a broader explanation of how residential buildings, installations, and household contents can be insured against different risks, you can also review Bima24’s Home Insurance / Residential Property Insurance service page.
Conclusion: Fire and Earthquake Are Different Risks Within the Same Insurance Structure
The main difference between fire insurance and earthquake insurance is that fire, explosion, and lightning are generally core fire insurance risks, while earthquake is usually an additional risk added to the same policy.
So, having basic fire insurance does not automatically mean your home is protected against earthquake damage.
A proper review should consider more than the name of the coverage.
You should also check:
- what property is insured
- the insured value
- the deductible
- the coverage limit
- exclusions
- special policy conditions
Because coverage terms may vary between insurance companies and policy types, the actual insurance contract should always be treated as the primary reference when determining whether a specific earthquake-related loss is covered.
FAQs
Does fire insurance cover earthquake damage?
Only if earthquake risk has been specifically included as an additional coverage. Basic fire insurance generally covers fire, explosion, and lightning.
Is earthquake insurance separate from fire insurance?
In many Iranian insurance products, earthquake is offered as additional coverage under a fire insurance policy rather than as a completely separate policy.
What does earthquake insurance for a home cover?
It may cover eligible earthquake-related damage to insured property, subject to the insured amount, deductible, coverage limits, exclusions, and other policy conditions.
How do I know if my policy includes earthquake coverage?
Check the insured risks, special conditions, and endorsements. Earthquake or earthquake and volcanic activity should be explicitly listed.
Does earthquake coverage include household contents?
It may, provided household contents are included as insured property and earthquake coverage applies to them.
Can tenants get earthquake coverage?
Tenants may insure their own household contents and personal property, depending on the insurer’s product and conditions.
Is basic natural disaster building insurance the same as earthquake coverage?
No. Basic natural disaster building insurance is a separate insurance mechanism and should not be confused with optional earthquake coverage under commercial fire insurance.
Does fire and earthquake insurance cover bodily injury?
Standard fire insurance for buildings and contents is primarily property insurance. Bodily injury normally requires separate or additional insurance coverage.
No comment